5 questions about real estate lead referral fees, answered
A real estate lead referral fee of 20 percent is negotiable, not a fixed U.S. standard. Referral fees commonly range from 20% to 35% of the receiving agent’s commission, with 25% often used. Payment is generally made only if the referred transaction closes.
The percentage matters, but so does what it applies to: referral fees are generally calculated from the commission on the referred side, not the home’s sale price. Before making an introduction, agents should agree on the fee and put the terms in writing.
This guide answers five practical questions: how agents negotiate referral fees, what the agreement should cover, when it expires, and how published rates across lead programs compare. You’ll get a clearer basis for assessing whether a 20% arrangement fits the referral and the work involved, rather than treating one percentage as the rule for every deal.
Key Takeaways
- Make the written agreement specific about the referred client, covered transaction, payment trigger, and fee calculation.
- Set a clear agreement term and define what happens if the client returns after it ends.
- Broker authorization and the nature of the referral matter; RESPA restricts certain payments tied to settlement services.
- Published rates vary across lead programs, so compare the fee structure and referral terms, not just the percentage.
- Use the article’s framework to assess whether a referral arrangement fits your business model and the work involved.
1. Are referral fees negotiable?
Yes. Agents can negotiate referral fees before introducing a potential client, and the agreed percentage should reflect the referral’s value. U.S. referral fees commonly range from 10% to 50% of the receiving brokerage’s commission. The lead’s qualification, the referring agent’s involvement, and the relationship between agents can all influence the negotiated rate.
Calculate the fee from the commission earned on the referred side, not the property’s sale price. The receiving brokerage may then apply its own split, so distinguish gross commission from the agent’s eventual take-home amount.
Agree on the calculation before sharing the seller’s details. Specify whether the percentage applies to gross commission, which transaction side counts, and what event triggers payment. A written agreement helps prevent disputes about the amount or timing and protects the business relationship.
Read the Redfin Partner Program’s governing terms for its fees and payment deadlines. Don’t assume its rate matches a negotiated agent-to-agent referral or that payment arrives on closing day. The agreement controls how the fee is calculated and when the brokerage must process payment. Timing may differ from the closing date because the referral must be documented and handled through the brokerages.
The payment model also affects your risk. With pay-at-closing referrals, the fee is generally due only if the transaction closes. Upfront lead costs are paid before a sale, so the agent bears the cost if a lead does not convert. Compare that exposure with a closing-based fee, and assess lead quality alongside the percentage.
Tax reporting has a separate threshold. According to the Internal Revenue Service, the federal reporting threshold for 1099-NEC and 1099-MISC forms was $600 before it rose to $2,000 for qualifying payments after December 31, 2025. According to the Internal Revenue Service, for payments made after December 31, 2025, that federal reporting threshold rises from $600 to $2,000. Reporting thresholds don’t determine whether referral income is taxable.
2. What is a real estate referral fee?
Buyer, seller, and commercial referrals can have different terms because each transaction has its own commission structure. The fee is usually calculated from the commission on the referred side, while commercial agreements may define payment around the specific transaction or brokerage arrangement.
A referral fee is compensation paid to the agent who connects a client with another real estate agent. In the United States, 25% of the gross commission on the referred side is commonly used. Typical rates range from 20% to 35% of that commission, though the agents can negotiate the percentage before making an introduction.
Here’s how the calculation works: one example uses a $100,000 home purchase, with each agent receiving $3,000 after the commission split. A 25% fee on the receiving agent’s $3,000 commission pays the referring agent $750. The fee comes from commission, not directly from the home’s sale price. Confirm which side and commission amount the written terms cover.
Referral rates can reflect the work behind the introduction. A 10% fee may fit a lead that required little qualification, while 50% may reflect a close relationship and substantial relocation support from the referring agent. A real estate finder’s fee may range from 5% to 35% of an agent’s commission. These examples show why one “typical” percentage cannot capture every lead’s value.
Before accepting an agent referral, consider how qualified the contact is, what support the referring agent provides, and whether the fee leaves enough commission for your work. A warm introduction to a ready seller is different from an unqualified name. The written agreement should identify the client and covered transaction so both agents know when the fee applies.
Tax reporting depends on the payment and applicable reporting threshold. According to the Internal Revenue Service, for payments made after December 31, 2025, the federal reporting threshold for 1099-NEC and 1099-MISC forms rises from $600 to $2,000. A reporting threshold does not, by itself, make referral income tax-free.
For agents developing a seller-side pipeline, affluent seller leads offer another route to connect with potential listing clients. Compare that lead source with agent referrals by considering qualification, commission terms, and the work required to convert each opportunity.
3. Written referral agreements
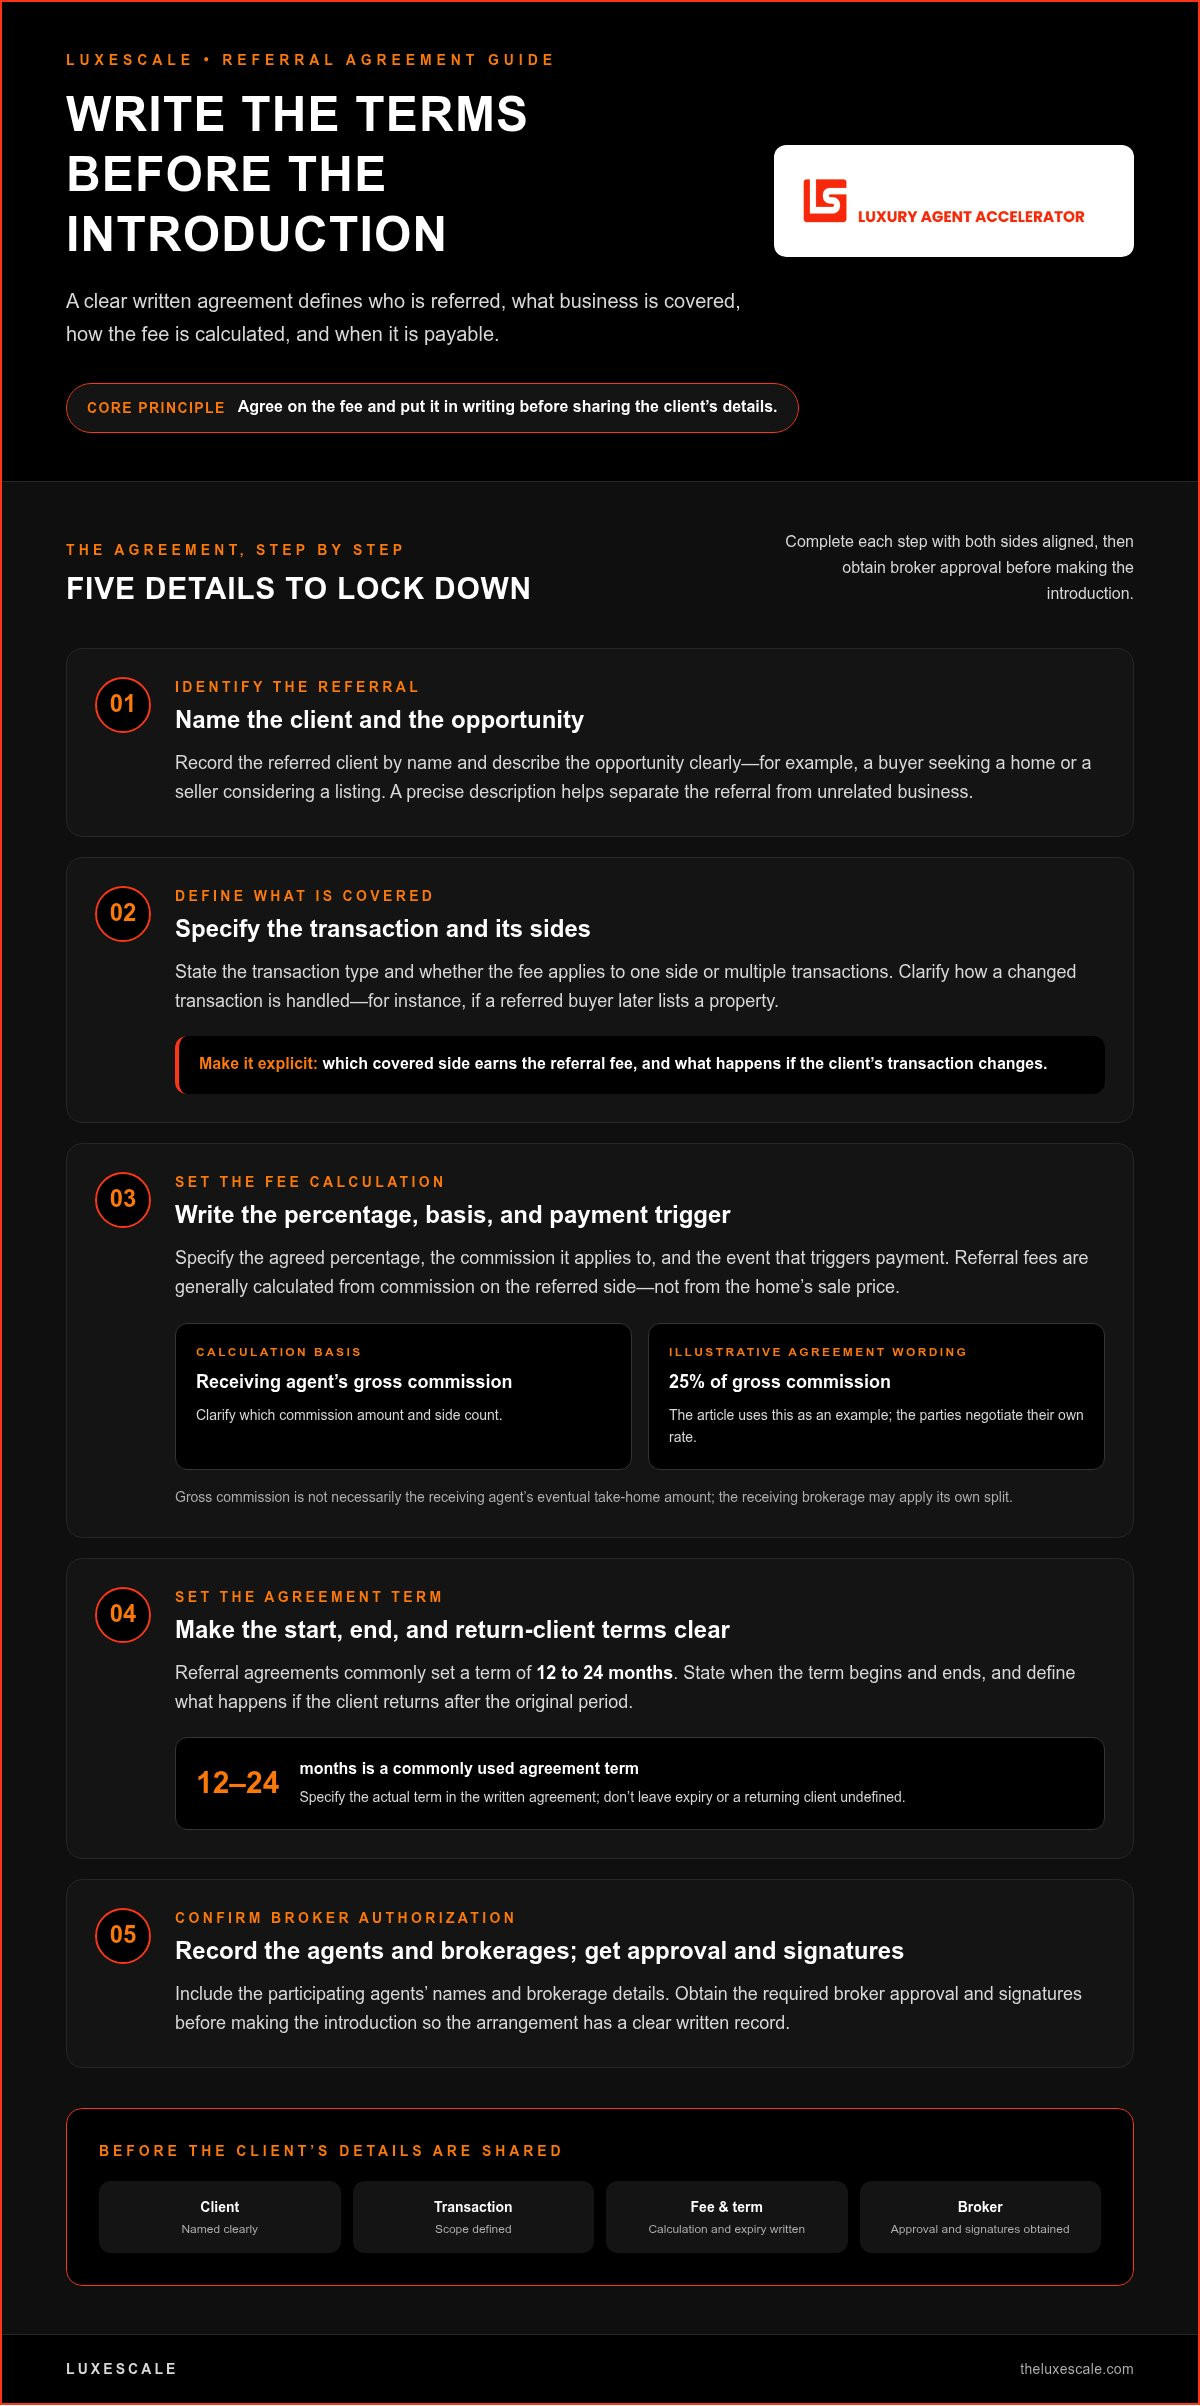
A written referral agreement records the terms between the referring and receiving agents. It identifies the client, covered transaction, fee calculation, and event that triggers payment. Recording those details before sharing the client’s information gives both sides a clear account of the arrangement.
Referral agreements commonly set a term of 12 to 24 months. The agreement should state when the term begins and ends, and whether it covers a client who returns after the original period. Define the referral by name and transaction type, such as a buyer seeking a home or a seller considering a listing. Precise descriptions help agents distinguish the referred opportunity from unrelated business.
Write the commission terms so the brokerages can calculate the fee consistently. Specify the percentage, the commission it applies to, and whether it covers one side or multiple transactions. For example, if the agreed fee is 25%, clarify that it applies to the receiving agent’s gross commission on the covered side. State how the parties handle a changed transaction, such as a referred buyer later listing a property.
Broker authorization matters. A real estate referral agreement must be authorized by a licensed broker to be considered legal and binding. Include the participating agents’ names and brokerage details, then obtain the required broker approval and signatures before making the introduction. A handshake may establish intent, but it does not provide the same written record of the agreed terms.
Templates can help organize the agreement, but the completed document must reflect the actual client relationship and transaction. Review every clause instead of relying on a blank form. Include:
- The client’s identifying details and the referral date.
- The covered service, transaction side, and fee calculation.
- The agreement term, payment trigger, and handling of repeat business.
- The agents’ brokerage information, broker authorization, and signatures.
In many markets, an agreement may specify payment on the first deal if the client’s purchase price is at least $100,000. Treat that as a term to define clearly, not an assumption that applies to every referral. A signed agreement should answer what qualifies as the first deal and how the fee is calculated.
Before forwarding the client’s contact details, compare the final document with the conversation that established the referral. Confirm that the percentage, covered transaction, term, and signatures match. This final review helps prevent avoidable disagreements and gives each brokerage a clear basis for processing payment.
4. Do referral agreements expire?
Yes. A referral agreement can expire when its stated term ends, so the document should define the start date and expiration event. Real estate referral agreements commonly set a term of 12 to 24 months. The contract should also clarify whether a transaction involving the referred client remains covered if it closes after expiration.
Expiration terms matter when a client takes time to act. For example, an agreement can explain whether a lead introduced during its term qualifies if the client later buys or sells. Define the covered client, transaction, and payment trigger in plain language. This gives both brokerages a shared basis for determining whether a fee is due.
Referral percentages themselves aren’t set by state statute, and no state caps referral percentages by statute. The agreed rate and payment terms still belong in a written contract, with broker authorization. A 35% fee, for example, should state the commission base and transaction side it covers. An expired agreement can create disagreement if those details don’t address later activity.
Federal rules add a separate consideration. Section 8 of the Real Estate Settlement Procedures Act, or RESPA, governs certain referral payments connected with home purchases. RESPA restricts referral payments involving settlement-service providers, such as lenders and title companies. Its Section 8 is identified as 12 U.S.C. 2607. These provisions concern settlement-service referrals, not simply the percentage agents negotiate between brokerages.
Referral-payment rules can depend on the parties and circumstances, so confirm that an arrangement complies with applicable requirements. A licensed agent’s referral arrangement must still be handled through the brokerages and comply with applicable rules. A signed agreement does not authorize a payment that RESPA restricts.
A 20% fee can lead to disputes if agents disagree about the commission base, the covered transaction, or whether the referral caused the closing. Conflicting expiration dates or missing broker approval can complicate payment, too. Clear contract language addresses each point before the client is introduced.
RESPA violations can carry fines of up to $10,000 and one year in prison per violation, as well as liability of three times the charge in private suits. These consequences make the payment’s purpose and recipient important, especially when a transaction involves a lender, title company, or other settlement-service provider.
Before a referral agreement ends, review its term against the client’s transaction status. Record whether the client has entered a covered deal, whether the payment condition has occurred, and which brokerage processes the fee. This final review helps agents apply the written expiration terms consistently and distinguish ordinary brokerage referrals from restricted settlement-service payments.
5. Published referral-fee rates across lead programs
Published rates show how lead programs price access differently from agent-to-agent introductions. Corporate relocation firms commonly charge 35% to 40% of the commission for referral business. Some agents advertise 30% or 35% to attract referrals, while real estate platforms commonly charge 30% to 40%. These figures create useful comparison points, not one universal rate.
The pattern matters: a real estate lead referral fee of 20 percent sits below those published platform and relocation ranges. That difference alone doesn’t establish which arrangement offers better value. Compare the fee with the referral’s qualification, the amount of work required, and whether payment is triggered by a closed transaction or charged upfront.
Lead programs can differ in what the referring party contributes. A referral may come with an introduction, while lead generation can involve identifying and qualifying a prospective buyer or seller. A clear explanation of the program’s role makes it easier to judge whether its percentage fits the work and opportunity delivered. A listed rate without a clear commission base tells only part of the story.
Read each published rate alongside its payment terms. Confirm whether the percentage applies to the receiving agent’s commission, which transaction side is covered, and what event makes payment due. A 30% rate charged only after closing has a different cash-flow profile from an upfront lead charge. The parties should also understand who processes payment and what happens if the transaction changes.
Assess the economics using your own conversion history, not the advertised percentage alone. A higher rate may leave less commission from a closed deal, while an upfront model puts costs on the agent before a sale. Compare qualified opportunities, closing outcomes, and follow-up time. These factors show whether a lead program can support sustainable income more clearly than its headline rate.
For a licensed agent, the practical comparison is between the full terms and expected work, not simply 20%, 30%, or 40%. Review the agreement, identify the payment trigger, and calculate the fee against the commission base it names. Then weigh the lead’s readiness and fit with your market. This process keeps the rate in context and makes competing program structures easier to evaluate.
Want to build a seller pipeline through a referral-based model? Explore lead opportunities for real estate agents and consider how the program’s qualification and closing terms align with your business.
LuxeScale: Luxury Listing Appointments
LuxeScale helps agents build a luxury-market pipeline by identifying and qualifying affluent homeowners ready to sell, then scheduling Luxury Listing Appointments. Its performance-based model charges a 20% referral fee at closing, with no monthly or recurring out-of-pocket charges. Agents can also access Affluent Seller Leads, Affluent Buyer Leads, and accompanying award-winning training, coaching, systems, and support. This is a fit for agents seeking qualified opportunities and a closing-based referral arrangement rather than upfront lead costs.
If you’re evaluating your next source of luxury-market opportunities, visit LuxeScale to learn more.
Build Your Next Referral Channel
Your next growth decision is about fit: choose opportunities that align with the clients you serve and the business you want to build. A real estate lead referral fee of 20 percent is only one part of that decision. The quality of the opportunity and the support behind it shape how effectively you can turn a connection into lasting client relationships.
For agents focused on the luxury market, LuxeScale connects that growth goal with Luxury Listing Appointments and Affluent Buyer Leads. Accompanying award-winning training, coaching, systems, and support can help you make the most of those opportunities. Consider which client pipeline you want to develop next, then take a deliberate step toward it.
Contact LuxeScale to discuss your leads and explore whether its opportunities align with your business. Your next step can be focused, practical, and built around the market you want to serve.
Frequently Asked Questions
Are referral fees negotiable?
Yes, agents and their brokerages can negotiate the fee before sharing a client’s details. A real estate lead referral fee of 20 percent is one possible arrangement, not a fixed rule. Consider how qualified the lead is, what support the referring agent provides, and how the fee affects the receiving agent’s commission. Record the final terms before the introduction, so both parties know what they’ve agreed to.
What is a real estate referral fee?
A real estate referral fee is compensation for connecting a prospective buyer or seller with an agent who handles the transaction. The referring agent typically receives an agreed share of the receiving side’s commission if the deal closes. For example, an introduction could connect an out-of-market buyer with a local agent who understands the buyer’s needs. The written terms determine which client and transaction qualify.
Do referral agreements expire?
Yes, referral agreements can expire when their stated term ends. The practical detail is how the agreement treats a client who acts near or after that date. For example, specify whether a purchase contract signed before expiration remains covered if closing happens later. Also define how the parties handle a repeat transaction or renewed agreement, rather than assuming coverage continues.
Why do agents and brokers make referrals?
Agents and brokers refer clients when another professional is better positioned to serve a buyer or seller. An agent may need a trusted contact in a different market or lack the capacity or expertise for a particular transaction. The referral can preserve the client relationship while connecting the client with relevant representation. The referring professional may receive agreed compensation if the referred transaction closes.
Can anyone earn a referral fee?
No. Real estate referral fees are generally paid between licensed real estate professionals through their brokerages. An unlicensed person shouldn’t expect to collect a fee simply for introducing a buyer or seller to an agent. Licensing status and the arrangement’s purpose matter, particularly when settlement-service providers are involved. RESPA restricts certain referral payments connected with home purchases, so payment structures must respect those limits.
Does a referral fee take money away from the buyer or seller?
Usually, the referral fee comes from the receiving brokerage’s commission, rather than being charged to the buyer or seller as a separate referral bill. The fee reduces the commission available to the receiving side according to the agreed terms. Agents should distinguish the client’s transaction costs from the brokerage’s internal payment arrangement. The client’s purchase or sale documents govern the charges the client actually owes.
How is the pay-at-closing referral fee calculated?
First identify the commission earned on the referred side. Then multiply that amount by the agreed referral percentage. For instance, if the receiving side earns a gross commission, the referral fee equals that commission multiplied by the contract rate. The fee is typically payable when the referred transaction closes. The brokerage split is calculated separately, so the receiving agent’s final earnings may be lower than the gross commission remaining after the referral payment.
How much do you keep on a typical sale?
The amount depends on the commission earned, any referral payment, and the agent’s brokerage split. As an illustration, a $400,000 sale with a 5% total commission produces $20,000 in total commission. An even split gives each side $10,000. If the receiving agent pays a 25% referral fee on that $10,000, $7,500 remains before the agent’s brokerage split, taxes, and other expenses.
Article by
Mark Coppens
Mark Coppens is the Founder and Chairman of LuxeScale and Co-Team Lead of Living Vogue | eXp Luxury. He is an active elite-level luxury agent and the author of the upcoming book, POWER POSITIONING: From Missiles to Mansions – Why People Really Buy, and is a nationally recognized speaker on luxury real estate, consumer psychology, marketing, and business growth.
A U.S. Army veteran with an MBA in Marketing, Mark has generated more than $1 billion in career sales and now leads one of the nation's fastest-growing luxury referral platforms, referring more than $2 billion in luxury real estate opportunities each month to partner agents across the United States. He specializes in helping real estate agents generate more listings, break into the luxury market, and build scalable businesses through qualified referrals, award-winning training, coaching, and proven systems. His practical, psychology-driven approach has helped agents across the country increase their income while attracting more affluent clients and building lasting, referral-driven businesses.